

A home loan can turn stable salary income into a long-term housing asset, but the EMI is only one part of the decision. You will be able to test affordability, calculate the cash required, compare loan terms, and identify property or employment risks before deciding whether to buy, rent, wait, or choose a smaller home.
Key takeaways
- Compare EMI with rent and every ownership cost before deciding.
- Keep room for maintenance, taxes, insurance, repairs and registration cash.
- Check your credit history, income records and existing loan obligations early.
- Compare total repayment, fees and prepayment terms—not just the interest rate.
When Does a Home Loan Make More Sense Than Renting or Waiting?
A home loan makes sense only when you expect to stay in the property for several years and the full ownership cost fits your income. Compare the proposed EMI plus maintenance, property tax, insurance, repairs and registration-related cash with rent, expected savings, family needs, job stability and the likelihood of relocating.
| Option | Financial effect | Better choice when |
|---|---|---|
| Renting | Preserves cash and mobility | Your job, city or family plans may change |
| Waiting | Builds down payment and emergency savings | Current EMI would consume savings capacity |
| Smaller home | Reduces EMI and ownership costs | A preferred locality matters less than resilience |
| Buying now | Builds ownership but locks cash | You will stay long-term and retain reserves |
Do not stretch for a preferred Hyderabad locality if a smaller home lets you keep six months of essential expenses after purchase. A personal loan is not a shortcut: it usually has a shorter repayment period and higher cost, while property funding still requires title checks and substantial cash for the down payment and charges.
Under the old tax regime, eligible self-occupied borrowers can generally claim Section 24(b) interest deduction up to ₹2 lakh a year, while qualifying principal repayment and stamp-duty or registration payments fall within the ₹1.5 lakh Section 80C limit. Tax savings must not rescue an unaffordable EMI.
Stress-test a rate increase, lost variable pay, job change, relocation and unexpected household costs. Should salaried borrowers consider home loans in Hyderabad? Buy only when the payment works without bonuses and an emergency reserve remains after purchase.
How Much Home Can Your Salary Safely Support?
Set your purchase ceiling from net monthly salary, not gross CTC. A safe home loan for salaried borrowers in Hyderabad leaves room for existing EMIs, household commitments, the proposed home EMI and ownership costs without relying on bonuses.
1. Write down net salary after tax, existing EMIs and recurring commitments. Subtract the proposed EMI, maintenance charges, property tax, home insurance, utilities and a repairs allowance. If the balance is thin, reduce the property budget.
2. Keep an emergency reserve after closing: usually several months of essential expenses and EMIs. Do not put every saved rupee into the down payment and then borrow for a medical bill, job change or repair.
3. Apply the RBI loan-to-value ceilings: financing can reach 90% for loans up to ₹30 lakh, 80% for loans above ₹30 lakh and up to ₹75 lakh, and 75% above ₹75 lakh, subject to lender and property conditions. Stamp duty, registration and documentation charges generally cannot be added to the property value for LTV calculation.
Keep cash separately for:
- Down payment
- Telangana stamp duty and registration charges
- Brokerage, legal review and valuation
- Processing charges
- Interiors and moving expenses
For a ₹60 lakh property with a ₹48 lakh loan, the down payment is ₹12 lakh before these costs. Insert the lender’s annual rate and tenure into EMI = P × r × (1+r)^n ÷ ((1+r)^n−1), where r is the monthly rate and n the number of months.
Add total interest (total EMIs minus ₹48 lakh) and every non-loan cost before deciding.
What Will a Hyderabad Lender Check Before Approving You?
Two employees with similar salaries can receive different decisions because lenders assess stability, not just income. They examine employer type, employment tenure, probation status, age at loan maturity, salary credits and documented fixed pay. Bonuses, incentives and allowances count only when regular and supported by records.
Credit assessment also covers your credit score, existing EMIs and other liabilities, recent credit applications, and repayment history. Missed payments, multiple recent enquiries or high obligations can reduce eligibility even when your salary is strong. This is central to salaried person home finance in hyderabad.
Prepare these items before applying:
- PAN or another identity proof, address proof, recent salary slips, Form 16 and Income Tax Returns when requested.
- Six to twelve months of bank statements showing salary credits.
- Your appointment letter or employment confirmation.
- Evidence of other income and liabilities, including rent, personal loans, credit-card dues and co-borrower obligations.
Reconcile the salary slips, Form 16, bank credits and income figure in your application. A mismatch can trigger questions or delay approval.
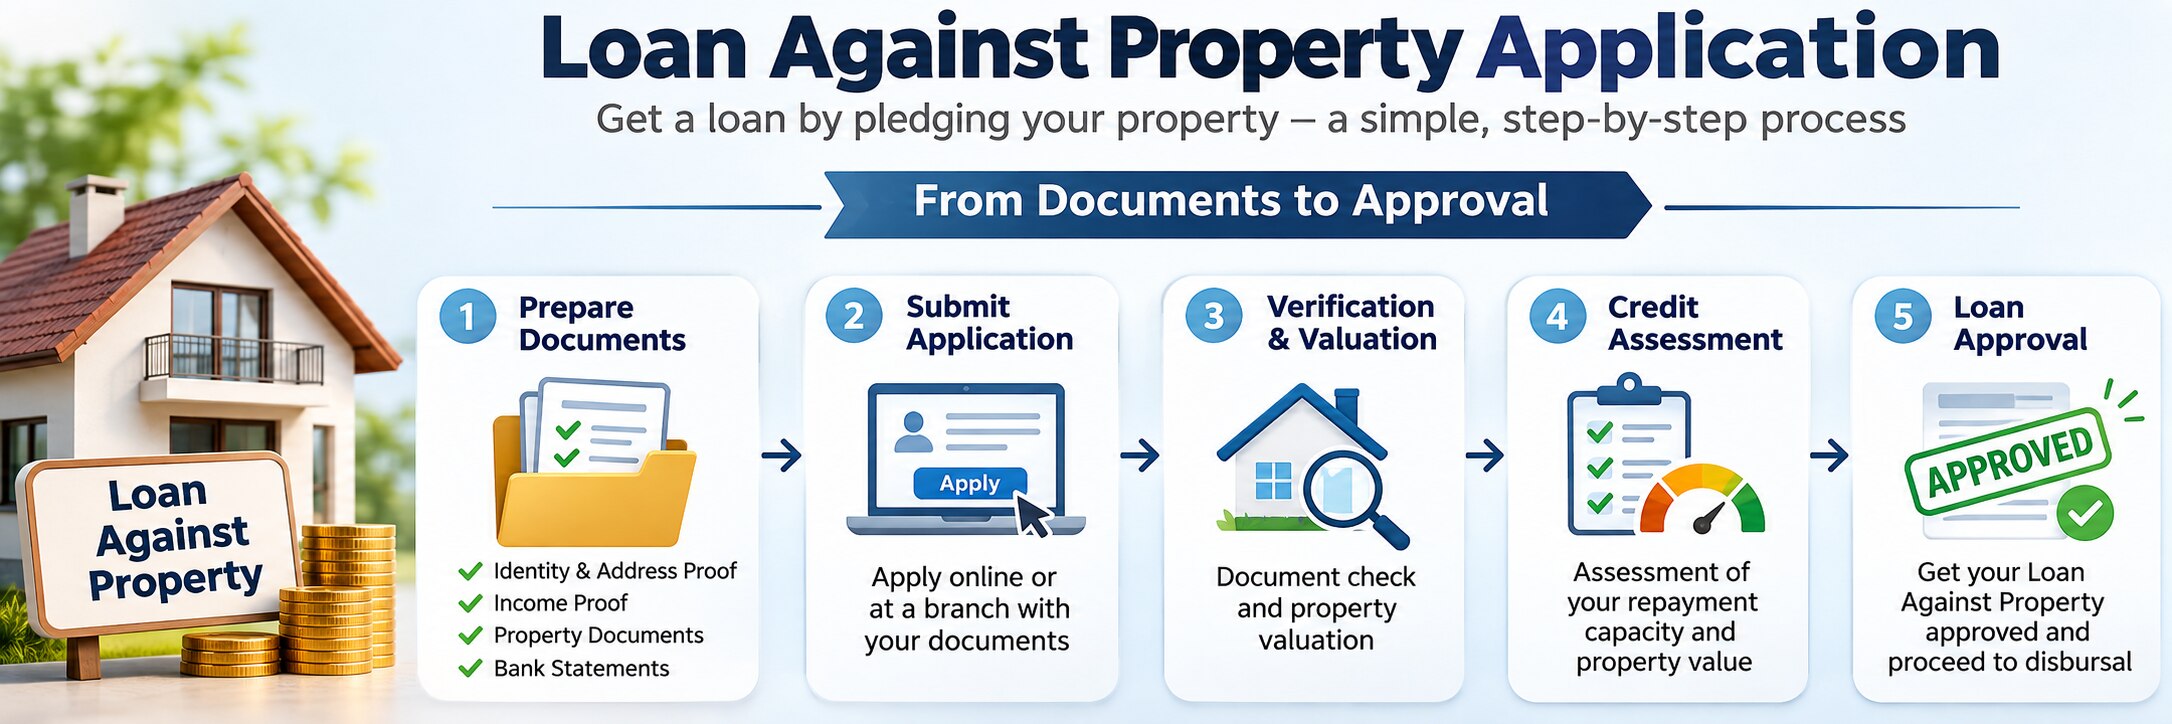
A sanction letter confirms borrowing terms subject to conditions; it is not property clearance or a guaranteed disbursement. For an under-construction home, the lender can release funds in stages against construction progress and demand letters, leaving you to pay pre-EMI interest and other cash costs before full EMI begins.
Which Loan Offer Costs Less Over Its Full Tenure?
The cheapest offer is the one with the lowest annualised percentage cost and total rupees repaid, not necessarily the lowest opening rate. For a home buying loan for employees in hyderabad, request each lender’s Key Facts Statement (KFS), annualised percentage rate, amortisation schedule and written fee list before accepting.
Ask the lender to itemise:
- Processing, legal, technical valuation and documentation charges
- Insurance, bundled products and every other fee
- Prepayment and foreclosure rules, part-prepayment conditions and minimum amounts
- Whether insurance is optional or tied to the loan
For a floating-rate loan, record the external benchmark, written spread, reset frequency, reset date and the EMI impact of a benchmark increase. Compare the spread, not just the introductory rate.
| Term | EMI effect | Total-cost effect |
|---|---|---|
| 20 years | Lower EMI | Higher total interest and longer exposure to rate changes |
| 15 years | Higher EMI | Less interest and faster repayment |
| 10 years | Highest EMI | Shortest repayment and usually the least interest |
Use the amortisation schedule to model annual part-prepayments without assuming a future bonus. Then test the EMI after a rate reset and confirm whether part-prepayment reduces tenure, EMI or both. A low introductory rate is not a bargain if fees, a wide spread or an unfavourable reset mechanism raises the long-term cost.
Compare written terms before comparing comfort.
Will the Property and Purchase Route Survive the Lender’s Checks?
A strong salary cannot rescue a property that fails legal or technical checks. A sanction is not clearance: for an under-construction home, disbursement follows construction progress and demand letters, while pre-EMI interest can strain cash before full EMI.
| Option | Lender’s property test | Common extra condition |
|---|---|---|
| Completed or under-construction home | Title, encumbrance, sanctioned plan, permissions and technical progress | Stage-wise release for construction |
| Plot loan | Chain of title, access, survey, approved residential layout and land-use status | Construction deadline or separate construction facility, lender-specific |
Before paying a substantial booking amount for a Hyderabad project, search the Telangana RERA portal for registration, promoter details, project status and complaints. RERA registration is separate from HMDA or another local authority’s land-use conversion, layout approval, building permission and occupancy certificate; it proves none of those by itself.
For an apartment, independent house or plot, have a property lawyer verify:
- Chain of title, encumbrance record, seller identity and survey details.
- Legal access, sanctioned plan, permissions and consistency with registration records.
- For a plot, approved residential layout and permitted use.
Ask the lender for its technical assessment and check its findings on construction and approvals. A loan-arrangement agency such as Home Loan, Mortgage Loan, Plot Loan in Hydererabad can compare bank and NBFC requirements for a home loan for salaried borrowers in Hyderabad or salaried person home finance in Hyderabad.
You still inspect documents, understand the KFS and retain cash reserves. Proceed only when income, total cash requirement, loan terms and property records all pass.
Related products
 | K V REDDY LOANS home loans , mortgage loans , loan against property mortgage loan process . In personal expenditure of varied needs like marriage, higher education, medical emergencies, business travel or any... |
 | BUSINESS LOANS PROCESS ( SECURED AND UNSECURED ) business loan process :--- we are providing business loans in hyderabad. secured business loans. View product → |
Frequently asked questions
When does a home loan make more sense than renting in Hyderabad?
Consider buying when you expect to stay several years and the EMI plus maintenance, tax, insurance, repairs and registration costs fit your income better than renting and waiting.
How much home can a salaried borrower safely afford?
Set the EMI only after accounting for household expenses, existing EMIs, savings, emergency funds and ownership costs; do not base the decision on salary alone.
What will a Hyderabad lender check before approving a salaried home loan?
The lender checks salary records, bank statements, credit history, existing debts, employment stability, identity and address documents, and the property’s legal and technical status.
How can you compare two home loan offers correctly?
Compare the interest method, total repayment, processing and legal fees, insurance charges, reset terms, EMI schedule and prepayment conditions across the full tenure.
Why can a property or purchase route fail a lender’s checks?
Approval can fail when title documents, approvals, construction details, seller records, valuation or the purchase agreement do not satisfy the lender’s legal and technical review.